Yes, you can legally leave India with massive credit card debt.
India with massive credit card debt. Credit cards are unsecured loans, and there is no “exit control” or Look Out Circular (LOC) routinely issued for unpaid credit card bills unless a court has specifically ordered it for suspected fraud or cheque bounce (e.g., if a NACH mandate or EMI check bounced).
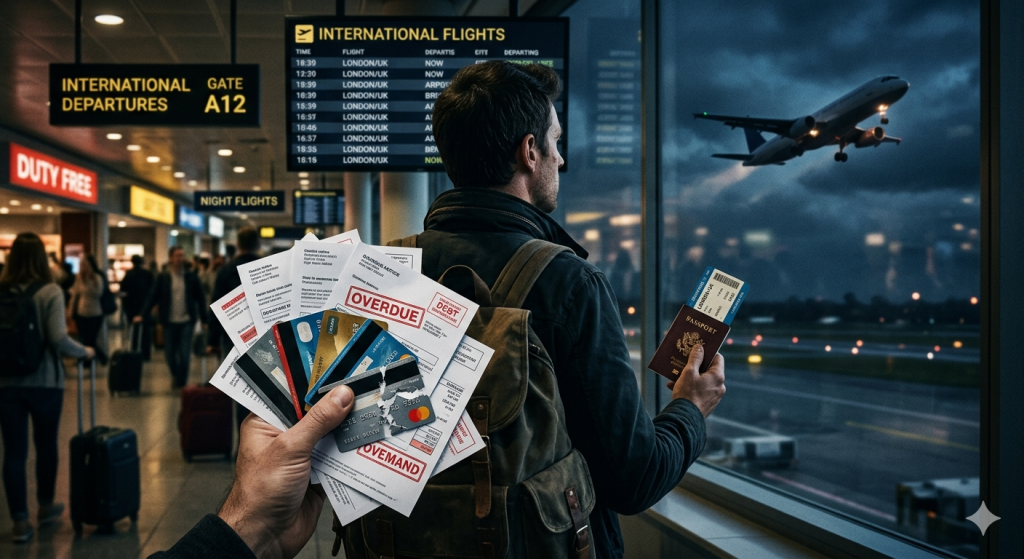
However, escaping the country does not erase the debt or its consequences.
What You Should Know
- Civil vs. Criminal: Defaulting on a credit card is fundamentally a civil matter. However, if the bank suspects fraudulent intent (e.g., maxing out the card with the immediate intention of fleeing) or if a debt repayment check bounced, they can pursue criminal charges under the Negotiable Instruments Act, 1881.
- Asset Seizure: While they cannot arrest you simply for non-payment, banks can legally pursue your assets in India (like property, gold, or bank accounts) through civil courts and recovery agencies to settle the dues.
- International Tracking: Banks frequently hire international debt collection agencies to track defaulters overseas. If you ever return to India, you may face legal summons, police verification issues for jobs or residency, and intense harassment from recovery agents.
- Credit Score: Your CIBIL or Experian credit score in India will be destroyed, which will block you from future credit in India.
To deal with massive credit card debt in India and prevent legal complications before or after you leave, you must shift from avoiding the bank to active negotiation.
Here is a step-by-step strategy to handle the situation.
1. Freeze the Debt Immediately
- Stop using the cards: Cut up the physical cards or lock them digitally to prevent compounding the debt.
- Stop automatic transfers: If you have automatic NACH mandates or standing instructions tied to your bank account, cancel them if you cannot fund them. Bounced automatic payments turn a civil debt issue into a criminal issue.
2. Initiate Communication with the Bank
- Do not go silent: Ignoring calls makes the bank assume you are a fraudulent “willful defaulter,” which triggers legal escalations.
- Write an official email: Contact the credit card division’s grievance redressal officer. State clearly that you want to pay but are facing financial hardship (e.g., job loss, medical emergency, business failure).
3. Negotiate a Settlement or Restructuring
Banks prefer getting some money back over spending years in court. You can propose two main options:
- One-Time Settlement (OTS): Ask the bank for a waiver on accrued interest and penalties. You can often negotiate to pay 25% to 50% of the total outstanding amount as a single lump-sum payment to close the account. Note: This will mark your CIBIL report as “Settled,” which hurts your credit score but legally ends the debt.
- Debt Restructuring / EMI Conversion: Ask the bank to convert the total outstanding balance into a fixed, low-interest EMI plan spread over 12 to 36 months. This stops the massive 40%+ annual credit card interest rates.
4. Appoint a Legal Power of Attorney (PoA)
- If you must leave India, appoint a trusted family member or lawyer as your legal Power of Attorney.
- Provide them the authority to handle bank communications, receive legal notices, and negotiate settlements on your behalf while you are abroad.
5. Respond to Legal Notices
- If you receive a legal notice (especially under Section 138 of the Negotiable Instruments Act for a bounced check), do not ignore it.
- Hire a lawyer to send a formal legal reply within the stipulated timeframe (usually 15 to 30 days) to prevent the court from issuing an arrest warrant.
6. Consider Formal Debt Relief Agencies
If negotiating alone is too stressful, you can hire regulated debt management or debt settlement agencies in India (like Freedom from Debt or SingleDebt). They will handle the recovery agents and negotiate settlements on your behalf for a fee.